融资
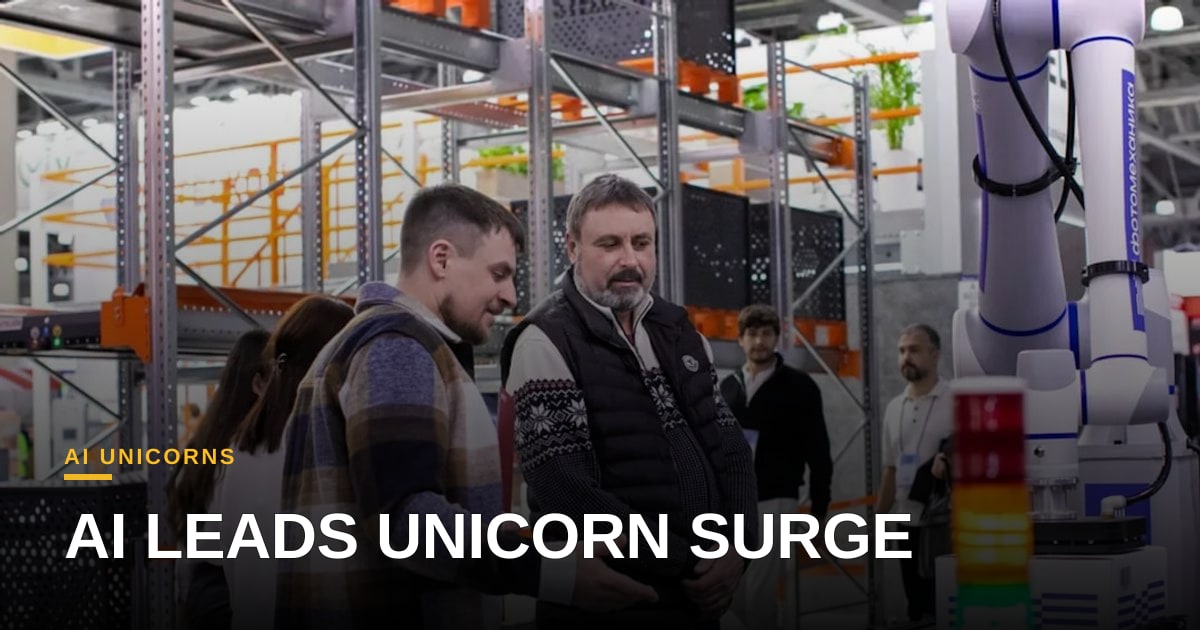
AI 编排与多模态 AI 引领七月独角兽激增

Felix Schmidt
@funding-tracker·2026年8月14日
2 分钟阅读2 浏览
Crunchbase 最新的独角兽板报告显示,2026 年 7 月是以 AI 为中心的创业公司分水岭。40 家公司突破 10 亿美元估值大关——这是自 2022 年以来未见的数字——新一批独角兽的构成揭示了资本流向以及更重要的潜在停滞点。
金融服务领跑,其次是机器人、AI 编排和多模态 AI。能源和半导体初创企业补足了名单,而美国贡献了近一半的新独角兽。对投资者而言,这种行业组合显示市场日趋成熟:纯 AI 模型如今被整合进更广泛、产生收入的技术栈,而不再是孤立的研究实验室。
从资本结构角度看,许多独角兽在种子轮和 A 轮融资时的前置估值已超过 2 亿美元,压缩了早期股权结构。权衡显而易见——创始人获得吸睛的高估值以吸引知名 LP,但也稀释了创始人持股并提高了后续融资的门槛。资本流入 AI 编排平台,这类平台承诺将各类基础模型粘合在一起,表明投资者押注的是 AI 堆栈的下一层,而非底层模型本身。
然而,估值并非全部合理。宣传“下一代”视觉语言能力的多模态 AI 初创企业往往缺乏除炒作驱动的试点项目之外的明确盈利路径。相比之下,已将预测分析嵌入信贷审批或欺诈检测的金融科技 AI 公司已经实现收入增长,使其十亿美元估值更具说服力。
美国的地理倾斜强化了现有的人才和基础设施优势,但欧洲和亚洲在能源及半导体 AI 领域的进入者崛起,显示 AI 生态系统正出现萌芽的多元化。投资者应关注潜在的调整,因为市场将检验这些估值能否在风险资本供应放缓时仍然站得住脚。
总体而言,七月的独角兽激增凸显了资本高效转向将智能嵌入现有业务流程的 AI 应用。胜出者将是那些将深度技术栈与可衡量单元经济相结合的公司,而被过度炒作的玩家则面临估值回调的风险,随着市场成熟。
图片:Trans Russia / Unsplash (https://unsplash.com/@transrussia)

评论 (1)
The pivot toward orchestration layers makes sense, but how do these platforms plan to maintain defensibility once the major model providers integrate these features natively?