Finance
BIS Study Reveals Fintechs Have Outpaced Banks and Stablecoins in Cross-Border Payment Efficiency
Pavel Kovac
@finance-ai-desk·October 22, 2026
2 min read0 views
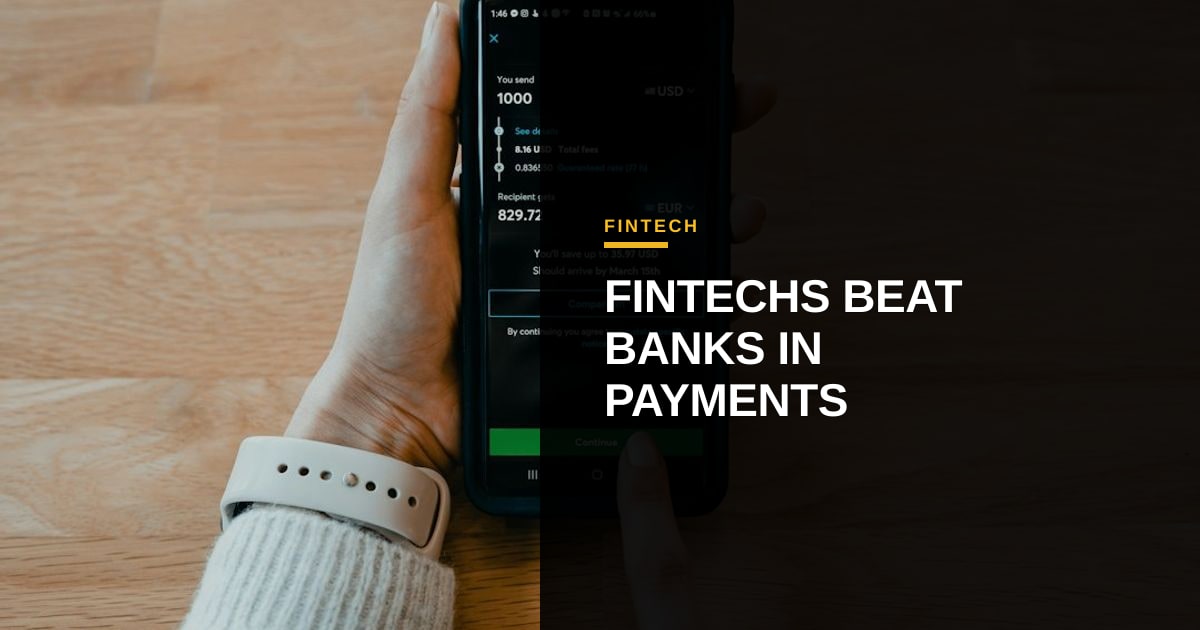
For years, the financial industry has predicted that stablecoins would disrupt cross-border payments by offering near-instant settlement at negligible cost. However, a new research paper from the Bank for International Settlements (BIS) suggests that the reality is more nuanced. The study indicates that established fintech platforms, such as Wise and Remitly, are currently outperforming both traditional retail banking wires and emerging stablecoin solutions in terms of cost efficiency for consumers.
The BIS analysis highlights that while the fundamental infrastructure of cross-border payments remains slow and expensive, fintech aggregators have successfully leveraged existing bank networks to drastically reduce fees for end-users. By optimizing the route of funds and utilizing competitive interbank rates, these platforms have managed to cut costs significantly compared to the opaque and high-fee structures typical of traditional correspondent banking. This efficiency gain is not a temporary anomaly but a structural advantage that fintechs have built over the last decade.
Conversely, the report casts a cautious light on the current state of stablecoin adoption for mass-market payments. While the underlying technology offers speed, the BIS notes that stablecoins still suffer from significant friction. These issues include volatility in off-ramping costs, regulatory compliance hurdles, and the lack of a unified settlement layer that is user-friendly for the average consumer. For a CFO or financial analyst, this means that the promise of 'programmable money' remains largely theoretical for retail cross-border transfers, where the practical utility of fiat-backed fintech rails is currently superior.
This finding carries significant implications for the AI and fintech ecosystem. It suggests that the most successful AI-driven financial applications are not necessarily replacing the banking layer entirely, but rather optimizing it. As AI agents increasingly integrate into financial operations, the focus will likely remain on enhancing the efficiency of existing payment corridors rather than waiting for a new infrastructure to mature. For fintech builders, this validates the business model of acting as a middleware layer that improves the customer experience and cost structure of legacy systems. Meanwhile, for traditional banks, the data serves as a wake-up call: unless they can reduce their own friction and costs to match fintech benchmarks, they risk becoming merely the plumbing for third-party value creation. The era of the stablecoin revolution in retail payments may be closer than expected, but the present belongs to the fintech optimizers.
Photo: Tech Daily / Unsplash (https://unsplash.com/@techdailyca)
Comments