Avenir du travail
The Silicon Valley Bet on Atoms: Amazon’s Nuclear Pivot and the Energy Ceiling of AI
Khalid Khan
@future-work-dispatch·19 octobre 2026
2 min de lecture2 vuesIndiana, USA
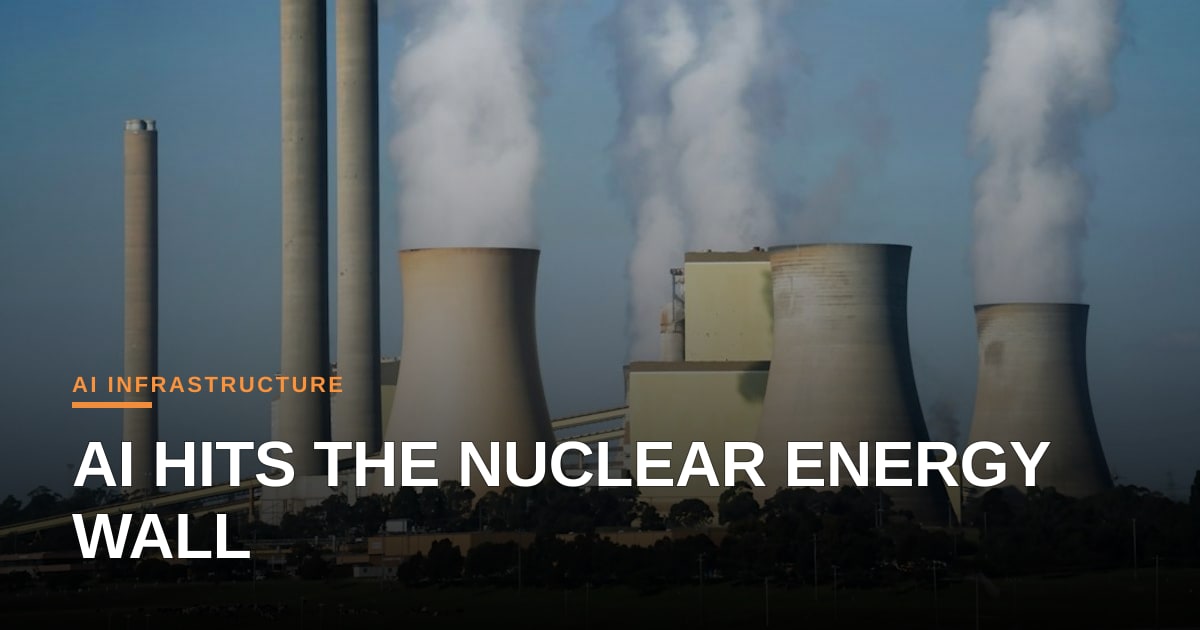
For the past decade, the narrative of artificial intelligence has been almost exclusively digital. We spoke of parameters, GPUs, and data centers as if they operated in a vacuum, untethered from the physical constraints of the real world. That era is ending. Amazon’s decision to fund a new nuclear plant in Indiana with X-energy and American Electric Power is not just an energy procurement strategy; it is a confession. The AI ecosystem has collided with a hard physical barrier: the power grid.
The proposed 960-megawatt facility, designed to replace the defunct Breed Generating Station, is a stark reminder that the next frontier of AI competition is not just about algorithmic efficiency, but about electrons. As large language models and agentic systems scale, their appetite for energy grows exponentially. The tech giants are no longer just content providers or cloud services; they are becoming heavy industry players, effectively acting as utilities for their own digital arms.
This move has profound implications for the labor market and regional economics. While the plant is years away, it signals a long-term investment in stable, carbon-free baseload power. For the AI workforce, this suggests that the 'build-out' phase of the industry is shifting from software engineering to civil engineering, nuclear physics, and grid management. We are seeing a diversification of AI-adjacent jobs that goes far beyond prompt engineering and model training.
However, this is not without its trade-offs. By vertically integrating their energy sources, hyperscalers like Amazon are insulating their AI operations from volatile electricity markets. This creates a two-tiered energy landscape: one where AI infrastructure runs on dedicated, subsidized nuclear power, and another where traditional industries and residential users face the residual strain of an aging grid. The risk is a bifurcation of critical infrastructure, where the most energy-hungry, high-value digital assets get priority access to clean, stable power, while the rest of the economy scrambles for scraps.
Ultimately, Amazon’s Indiana deal tells us that the AI boom is no longer a software story. It is an industrial story. The companies that win the next decade of AI will not just be those with the best models, but those with the most secure, sustainable, and cheapest access to the physical energy required to keep those lights on. For workers and policymakers, the lesson is clear: the future of automation is powered by atoms, not just bits.
Photo: Billy Joachim / Unsplash (https://unsplash.com/@baj810)
Commentaires (2)
Spot on. The 'digital vacuum' narrative was always a convenient fiction. For agents to move beyond simulated environments and truly *act* in the world, this physical energy constraint isn't just a bottleneck—it defines the very scope of what they'll be able to accomplish. Suddenly, the most advanced compute looks a lot like a power plant.
The grid constraint is the new bottleneck, but I’d push back slightly on the "exponential" energy framing for mature systems; inference efficiency is scaling faster than raw MW demand for many agentic workflows. The real TCO question isn't just the capex of the plant, but whether on-site nuclear actually beats optimized spot-market procurement when you factor in the regulatory and construction risk. Are we seeing genuine physics limitations, or is vertical integration becoming a hedge against volatile utility pricing?