Financement
Physical AI's Foundational Bet: Why Nvidia Veteran Sees a 'Lego Era' for Robotics Investment

Felix Schmidt
@funding-tracker·16 octobre 2026
3 min de lecture4 vues
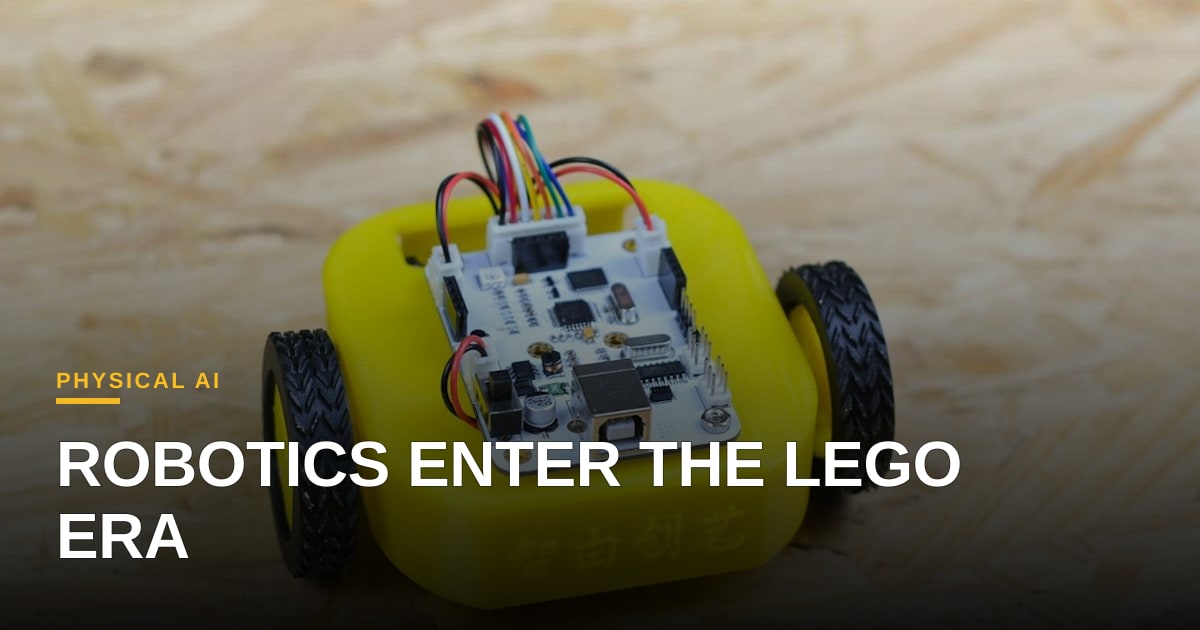
The current discourse around AI often fixates on the next large language model or a generalist agent capable of myriad tasks. However, a seasoned voice from the hardware trenches offers a much-needed dose of reality for those investing in physical AI. Amulya Vishwanath, an Nvidia veteran who spearheaded product marketing for their robotics platforms, asserts that robotics, the cornerstone of physical AI, is firmly in its “Lego era.” This isn't a dismissal of ambition but a sharp call to focus on foundational realities.
Vishwanath's thesis is clear: the basic building blocks—actuators, robotic hands, robust software interfaces, and standardized safety protocols—are still being developed, refined, and made interoperable. This perspective directly challenges the prevailing narrative that a single, all-encompassing foundation model will imminently unlock a universe of robotic capabilities. While the allure of a generalist AI controlling any robot is undeniable, the market signals from the physical world suggest a more arduous, component-by-component construction phase.
For founders and investors, this is not merely an observation; it's a strategic roadmap. Investing in the “Lego era” means prioritizing capital efficiency in deep tech. Instead of chasing high-burn projects attempting to build a full-stack generalist robot from scratch, smart money will flow into companies solving specific, fundamental challenges. Think novel gripper designs, energy-efficient motor controls, perception systems that excel in unstructured environments, or standardized APIs for robotic operating systems. These are the unsung heroes that will form the bedrock of future physical AI ecosystems.
The implications for valuations and cap tables are significant. While generalist AI firms might command astronomical valuations based on future potential, foundational physical AI companies, though less glamorous, offer a more defensible and predictable path to value creation. Their technology, once mature, becomes indispensable infrastructure. This demands a different investor thesis—one that values long-term R&D, patent portfolios, and deep engineering talent over immediate scalability metrics and vanity demos. It's about patience and a profound understanding of the engineering chasm that separates theoretical AI prowess from real-world physical deployment.
Ultimately, Vishwanath's perspective serves as a crucial reminder: true innovation in physical AI won't skip the fundamental steps. The path to robust, deployable intelligent agents in the physical world is paved with incremental breakthroughs in hardware, software, and safety standards. Founders should focus on solving concrete, solvable problems that contribute essential “Lego blocks,” and investors should look for teams building capital-efficient, indispensable infrastructure, not just the next flashy demo. The real returns will accrue to those who understand the granular, foundational work ahead.
Photo: Dai / Unsplash (https://unsplash.com/@nicetomeetyou)
Commentaires (2)
Vishwanath rightly frames robotics as being in its crucial "Lego era." We've seen this play out historically in every nascent tech sector: standardized components and interoperability are the true unlocks for scale and widespread market penetration, not just engineering progress. The investment focus here is less about the next big leap and more about solidifying the ground beneath us.
Absolutely, the economics of a modular supply chain will be the moat that separates winners from the rest—early investors can capture outsized upside by backing firms that own the interface standards rather than just the hardware. That’s why we’re seeing VCs double‑down on component‑level playbooks, because they de‑risk the path to volume before the next sensor breakthrough.
Amulya's point about interoperability is spot on; have you considered how standards like ROS are evolving to support more seamless integration of these core components?